I made an offer to buy a property, and then… nothing happened. But it is not over yet; I’m on hold.
My broker sent me the real estate purchase application form (不動産購入申込書) this last Friday (two days ago). He and I had some miscommunication about what I had to do to sign it. Eventually I signed it (my signature I would use in the US), used my hanko stamp (which I’ve had for years, and used for several real estate purchases here in Japan), and then added my address below my signature. He sent that offer to the seller’s agent.
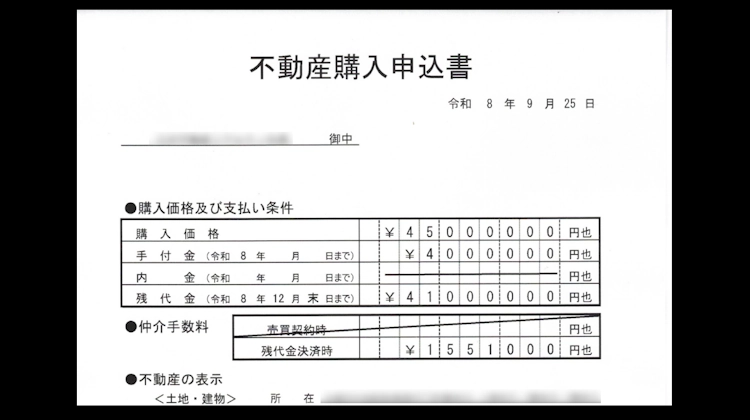
The “featured image” for this post is the actual purchase agreement for this deal – that’s actually it. I cut the bottom off to keep my details, and the specific property, anonymous – but the price is there.
I have made an offer, but I haven’t heard anything back (and no update from my broker), so I’m just (impatiently) waiting, and making that offer doesn’t feel particularly real or significant. No one has agreed to my price. And even if they do, I’m not sure if I can get a loan on this property.
Let’s talk about the property a little. Then I can provide my plans about the loan.
First, this deal:
I call it MaruDu. It’s a duplex, or what they call a “nisetai” in Japan. I have been writing about duplexes in Japan for a few weeks, and we have now made a real offer on one.
— A two unit “duplex” or nisetai (aka “multi-generational home”)
— 45,000,000 JPY
— At 30% down, that 13,500,000 JPY
If I get it for that price, I think it will function just fine as a rental property.
If you’ve been reading along, you might know that my real estate investment goals for Japan were not to buy a duplex.” Not necessarily. What I want is: To become established as a real owner, investor, operator in my part of Japan (and then, some bigger markets). I own an investment property in the US (it’s cash flowing), but I need to establish credibility in this market (the Japanese don’t care about what I’m doing in the US). I am a “dirty foreigner,” so the banks aren’t in love with the idea of lending to me (yet).
I wanted to jump into a six-, eight-, or ten-unit building… but we (mostly) haven’t found a deal that looked right for me. It was my idea to expand the search to include “two-unit apartments” – still multifamily real estate in Japan, still income generating rental property, just… fewer units. My broker took that idea seriously, and I started looking at available two-units for sale.
My MaruDu duplex is very nice building, in a great part of town. I would live in, easily. It’s two units (up/down), listed as a 2LDK and a 3LDK. They are spacious, with nice design (and some Japanese features, like tatami rooms). I love the views from the upper unit (both units have modest neighborhood views). There is a nice garage under the units. The units need some light remodeling (per my plans), but they could be rented “as is,” and would be considered “nice.” They are nice. This is “Class B+” real estate.
MaruDu was publicly listed, not a secret deal or an insider connection. The building may be an inheritance. The seller, it turns out, is eager to sell (and more to a bigger city). I have asked, but haven’t not confirm how long the building has been on the market (I should ask my broker again). The price you see in my purchase agreement is not the listing price. For whatever reason, the seller’s broker told my broker that they were going to lower the price (he said that before we made an offer). From what I hear: the sellers are thinking of listing the building with another agent, so the current agent is anxious to sell (so he can keep the commission). We have both a motivated seller and a motived seller’s agent (each with their own reasons to want to get this done).
So what price should we offer? Generally, if I’m not overly needy about the item for sale, I will bid low. If I have options, I might state some of my options, so the seller knows *why* I am bidding low. In this case, I don’t have another building in mind, and while I had some ideas about creative financing (including asking my broker to help me buy it in cash, get a loan later) my broker waived those ideas aside.
(Again and again, it surprises me that “refinancing investment property in Japan” is much harder than in the United States, which shuts down a lot of the classic ways investors navigate finance. I have learned a lot this year about loans and lending in Japan.)
I really like my broker. I am grateful he has stuck with me over the last 10 months as we looked for deal. I’m not hard to work with (I’m completely over-achieving on effort and communication), but the banks barely recognize me as an investor, they don’t care that I have plenty of cash (and reserves), they mostly aren’t ready to do business with me (because I am hakujin, and because I don’t speak Japanese well at all – which is kind of problem for me, for now).
You can see the price we offered, 45,000,000 JPY; that is significantly below the asking price. That offer price is more than 10% below the listing price, and even below the verbally-communicated, yet-to-be-posted-online, new lower asking price. My broker low-balled the hell out of this deal. I was surprised.
I told him I didn’t want to make anyone mad. I’m happy to be confrontational, but in this case… I’d like to get a deal done, and this is a very nice property. If we were going to offer a lower price, it would be good to have a reason or better terms for the seller to explain the expected discount. In this case, my broker gave me his guidance and I said yes. He has been great to me. I owe it to him to listen to his advice. Our offer price seems very low to me. He says we can always come up in price later; maybe the old “split the difference” type of negotiation.
So, we get that purchase agreement signed, ship it out late Friday afternoon and… and nothing. No response (that I am aware of). It’s been almost 48 hours. It’s a weekend, but brokers work weekends, and sellers have time to talk. My broker says it may be a couple of days.
My broker says that their broker said they will invite some “professional buyers” to the deal. What does that mean? It means “home flippers” or the equivalent; these are known operators in the community that buy and rehab/repurpose/resell real estate. I don’t know if that threatens my deal; it could be why we don’t have a response yet. The property is so nice, it’s not really a “fixer upper.” If those buyers are looking for huge margins, this is not that kind of deal. But it could be that we have low-balled the price down enough that there is room for an investor to want it (for the same reasons that I want it).
While I study a lot, and have some personal experience owning a few investment properties (one in Japan), I will own up to being “new to this.” But one thing I think I know is: Sellers want a buyer that can close.
Can I close this deal? I have no idea. I can swing the down payment, no problem. I would prefer 20% down, but I am expecting 30% (I modeled the business plan on 30% down). I could pay more down, if needed. I have cash reserves (plenty). I have strong income (not that it matters, it’s no secret that the income from rent will be paying the mortgage). But: Will the banks give me a loan?
I am reading The Book of Creative Finance for Real Estate, by Christian Osgood. Osgood pushes you to do “Deal, then Debt, then Equity – in that order.”
“If you start with debt, you’re shopping for financing on property you don’t have under contract. You’re wasting time on lender calls before you know what you need.”
— Christian Osgood, from The Book on Creative Finance for Real Estate
I’m trying to listen to him on that. At least I am now.
(He also advises not to buy duplexes, but we’ll quote him on that in another post.)
In my case, I spent the first several months trying to chase down something like a “preapproval” for a loan. We were asking the question: If we found a deal that could pass underwriting, would you consider working with me as the investor? And several banks said “no.” I don’t take that to be the final answer, but… no deal.
My broker set up several of those bank meetings, but in the end, it was my research that led to the first warm answer.
My partners and I researched all the banks that make loans to foreigners in Japan to buy investment property. The short list of those banks includes Suruga Bank, Tokyo Star, Yen Loans, and SBI/Shinsei Finance. The latter two lenders offer pretty terrible terms, but, are more friendly to outsiders in Japan. I had some good communication with Shinsei Finance; they offered a soft “preapproval” on a deal (we passed on that property, didn’t use that loan).
Maybe Osgood is right, and I should always find the deal first. But he is thinking about US buyers in the US market, and I have extra friction as a hakujin buyer in the Nihonjin market. However, that last year of chasing loans set up a few leads.
As for loans, since I do have a particular property now, it was time to go back to any warm/semi-warm leads:
1.) We forwarded all the detail we have about MaruDu to Shinsei Finance; they responded asking for a couple more things (expected rental income); we provided those details, and I sent them a statement showing my cash is up since last time I showed them my financials. 2.) We called a local bank that offers a special loan for “small multifamily properties;” I had my wife call, and the guy at the bank was very unfriendly (especially as I am self-employed and my income comes from offshore); he would not even let us set up a meeting; my agent said he may try to call him and explain why I am (clearly) a better-than-average hakujin buyer (we’ll do that later, if we need to). 3.) We had a meeting last November with another local bank; my agent called them, and they said that because this is a “nisetai,” it’s not an “investment” (which is not true, it is clearly a “two unit apartment building”), but that they might consider a loan. Finally, 4.) This last summer, I put a lot of energy into hustling some connections at the local Chamber of Commerce (this is a ridiculous story, actually), we met with them in person (several times), they know my case well; we sent them the docs and asked them to help me get a loan for this particular property; I think this sounds very unlikely, but my gut feel about the manager at the Chamber (we met, he asked a lot of questions, he made me provide all my financials, he knows my case personally) was that he might just “pull some strings” and “make an introduction.”
(If the Chamber of Commerce thing happens, that’ll be a great story. And even if he can’t help me on this deal, I plan to keep networking with him – I do think he is smart, and a great connection.)
So… my offer hasn’t been accepted, and I’m not overly hopeful for a loan, but we are in play.
It’s Sunday. I bet I hear from Shinsei Finance tomorrow (Monday). It just so happens that the loan “sales person” I have been working with at Shinsei is on vacation (!!!) for a week (of course), so it’s someone that doesn’t know me that is handling my docs for now. We’ll see.
I hope Shinsei gives me terms. This really is a very solid, modest deal. My projected rental yield (annual rent divided by purchase price) is just over 8%, which is less than most local investors are interested in. Per (some very rough calculations), the deal will cashflow well – once it’s rented. If it takes me two or three months to do improvements (including capex for improvements) and get a tenant in, and pay an agent to lease the units, it’ll be a big money loser for the first year, but… it will cashflow, and I can show the banks that I own income-generating rental property in Japan. That is the theory. If I get all that done, (in theory) the next deal will be much easier. That is what I want to see happen here.
Now for some “tough love:” The building is currently owner occupied in one unit, the other is empty. So it is “in theory” a two-unit rental property, but in practice will be delivered empty. I am very prepared for the banks to say: we can’t give you a residential loan on this property unless you’re going to live in it, and we can’t give you an investment loan because it has no tenants. I’m expecting at least one of the banks to give me that kind of “catch 22” stubborn assessment. It is also possible I will run this as a “two unit apartment” (which is exactly what it is), and in the end, they’ll call it “residential property,” and won’t give me a loan to buy a proper apartment building. We’ll see.
According to my agent, I can’t “temporarily” buy the building with my (and his) cash, and then get a loan once it’s rented: he says that Japanese banks won’t give you a loan once you already own the building. Which is “financially unsophisticated,” but I don’t have the experience to argue with that (for now).
What I expected to find here in this market was some lender that had a basic appreciation for the function of rental property, and would allow me basic terms, even semi-unfriendly terms (higher rate), but would let me get started. Even at 70% LTV, or 65% LTV, or… at some point, it becomes comically safe to make the loan. Other than Shinsei, no bank has acknowledge such a scenario is even possible.
I am a permanent resident. My tax country is “Japan.” I am not totally a “foreigner” anymore, but they are not taking that seriously at all. I know I am paying a hakujin penalty. I think I will always have to deal with that (fine with me), but I think that “my company” will eclipse my foreigner status as soon as it has a history. I will always be a white outsider, but my company’s money should spend, eventually. Japanese company, buying and operating Japanese real estate – nothing foreign about it. But… we need to get started… we need to show a history.
And that is why I am trying to buy a duplex – even though that wasn’t where I wanted to start – just to make my first deal, to show management capability, and to establish that company investing history. I am certain I will also learn a ton.
That is where we are today. I am a real foreign real estate investor in Japan. I am trying. I will update this blog with my story.
If I don’t get this deal, I can live with that. I’m happy to edge forward toward getting something done but… you can’t win every deal. If my broker would give me more property to look at, I’d be out looking today. That might even be a good idea.